 Your Indexed Universal Life Policy Owner Guide
IUL: Now What?
You have your financial vehicle. Now learn how to drive it.
An Indexed Universal Life (IUL) insurance policy is more than a document you place in a drawer. It is a financial vehicle with important features, responsibilities, limitations, and potential uses.
Understanding how to fund, monitor, and use your policy can make a meaningful difference in your long-term financial strategy.
Explore Your IUL GuideBecause Important Information Is Easy to Forget.
After speaking with your financial advisor, time passes and many of the details discussed about your Indexed Universal Life policy may be forgotten.
Research on the forgetting curve shows that newly learned information can fade rapidly without review.
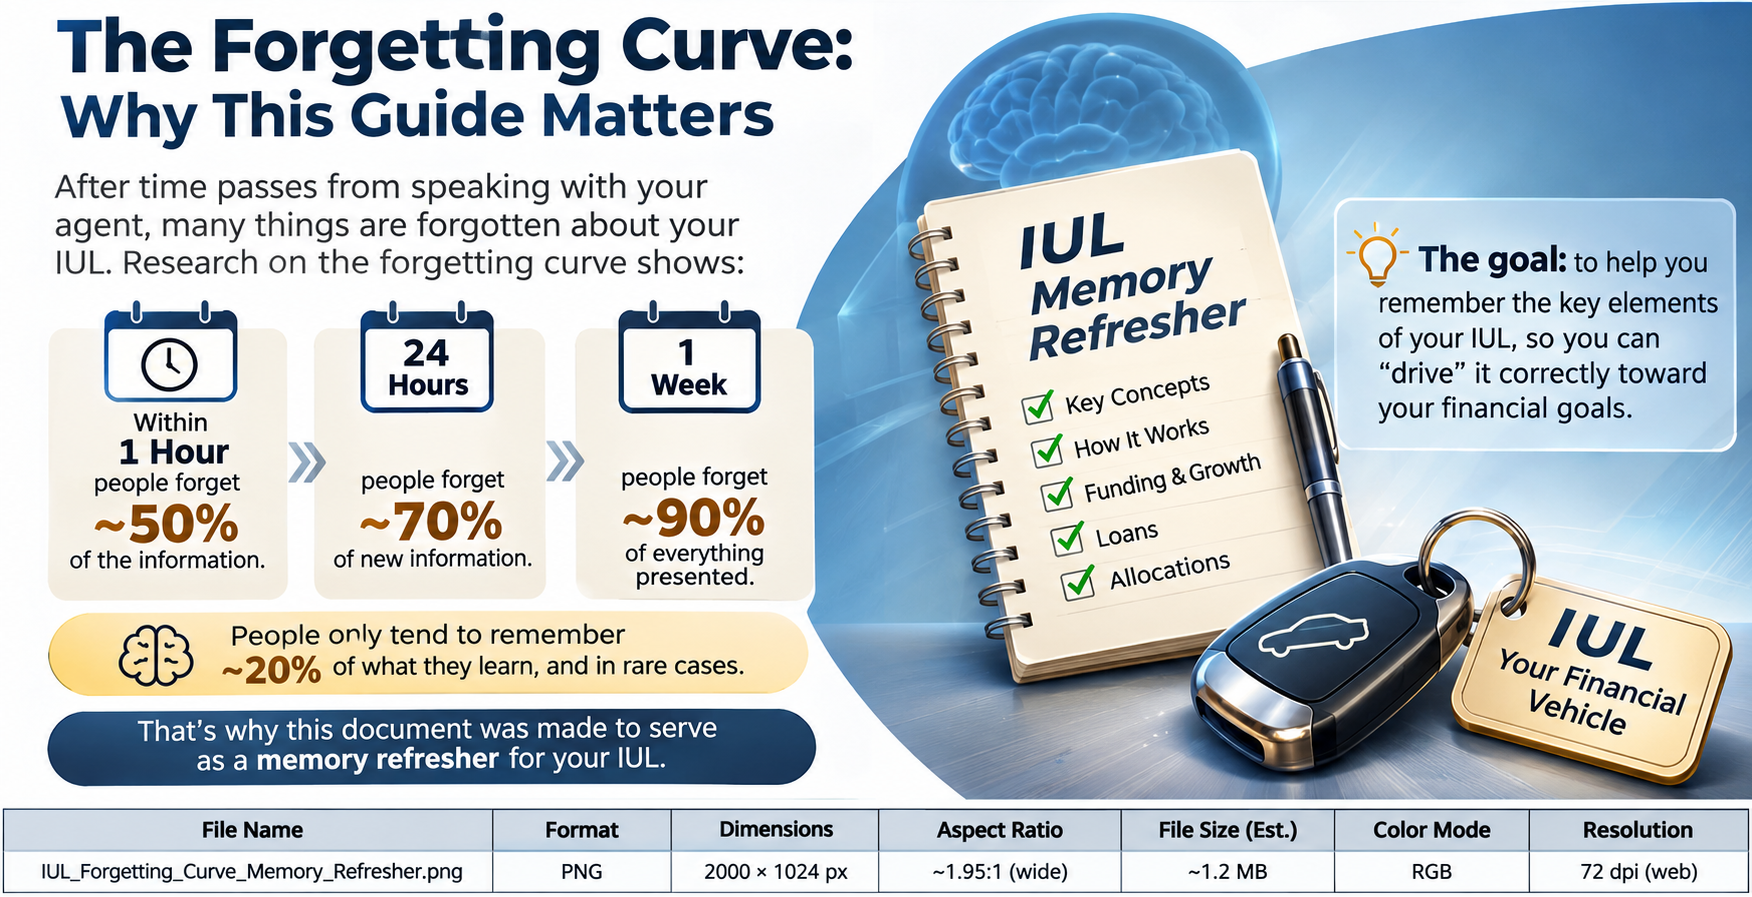
Popular explanations suggest that people may forget roughly 50% of new information within an hour, 70% within 24 hours, and as much as 90% within a week. Another commonly repeated statement is that people remember only about 20% of what they learn.
That is why we created this guide: to serve as a memory refresher you can return to whenever you have questions about your financial vehicle.
Your IUL Is a Financial Vehicle.
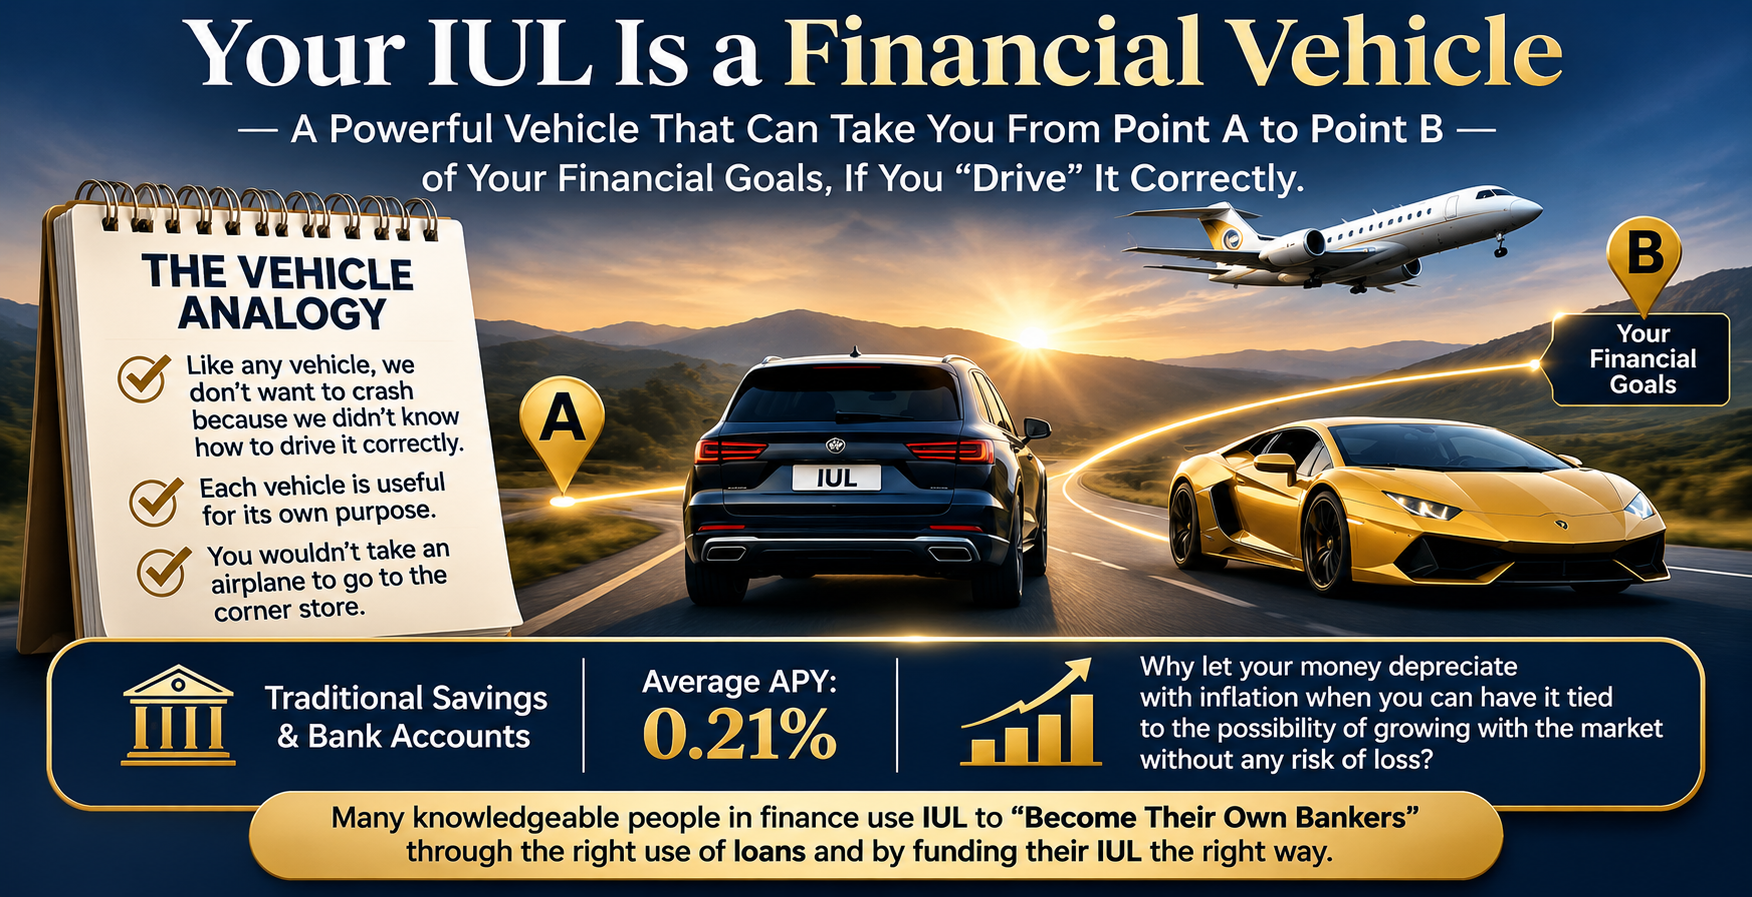
Think of your IUL as a vehicle that can help take you from Point A to Point B in pursuit of your financial goals, provided it is appropriate for your needs and managed correctly.
Like a car or an airplane, a financial vehicle has its own purpose, operating requirements, and limitations.
The last thing we want is to crash because we never learned how to operate our vehicle.
The Car
A car is practical for everyday transportation. You would not ordinarily use an airplane just to visit the corner store.
The Airplane
An airplane serves a different purpose. It can travel farther, but requires greater planning and knowledge.
Your IUL
An IUL combines permanent life insurance protection with the potential to accumulate cash value through contract-defined interest-crediting methods.
Each financial vehicle has appropriate uses. A savings account, a certificate of deposit, an investment account, and a life insurance policy serve different purposes.
Traditional savings accounts may offer relatively low yields. For example, an earlier comparison used an average savings APY of 0.21%. That figure is historical and should not be treated as a current market average.
Inflation can reduce the purchasing power of money held in low-yielding accounts. An IUL offers a different approach: interest credits may be linked to the performance of selected market indexes, subject to policy caps, participation rates, spreads, and floors.
Some financial strategies describe using permanent life insurance cash values to become your "own banker." This refers to accessing cash value through policy loans to help finance personal or business needs.
The concept can be useful in certain circumstances, but policy loans carry interest costs and risks, and should never be confused with withdrawing money from a traditional bank deposit.
How Much Can Your Financial Vehicle Hold?
Your IUL can accumulate money in its policy value. One important element of its structure is the Specified Amount (SA), which helps determine the policy's death benefit under its selected death benefit option.
Think of the Specified Amount as part of the design that determines how many passengers your financial vehicle can accommodate.
In our analogy, those passengers represent the money you may be permitted to contribute.
A larger death benefit may allow more premium funding before applicable tax-law limits are reached. However, it can also increase insurance costs.
Minimum. Target. Maximum.
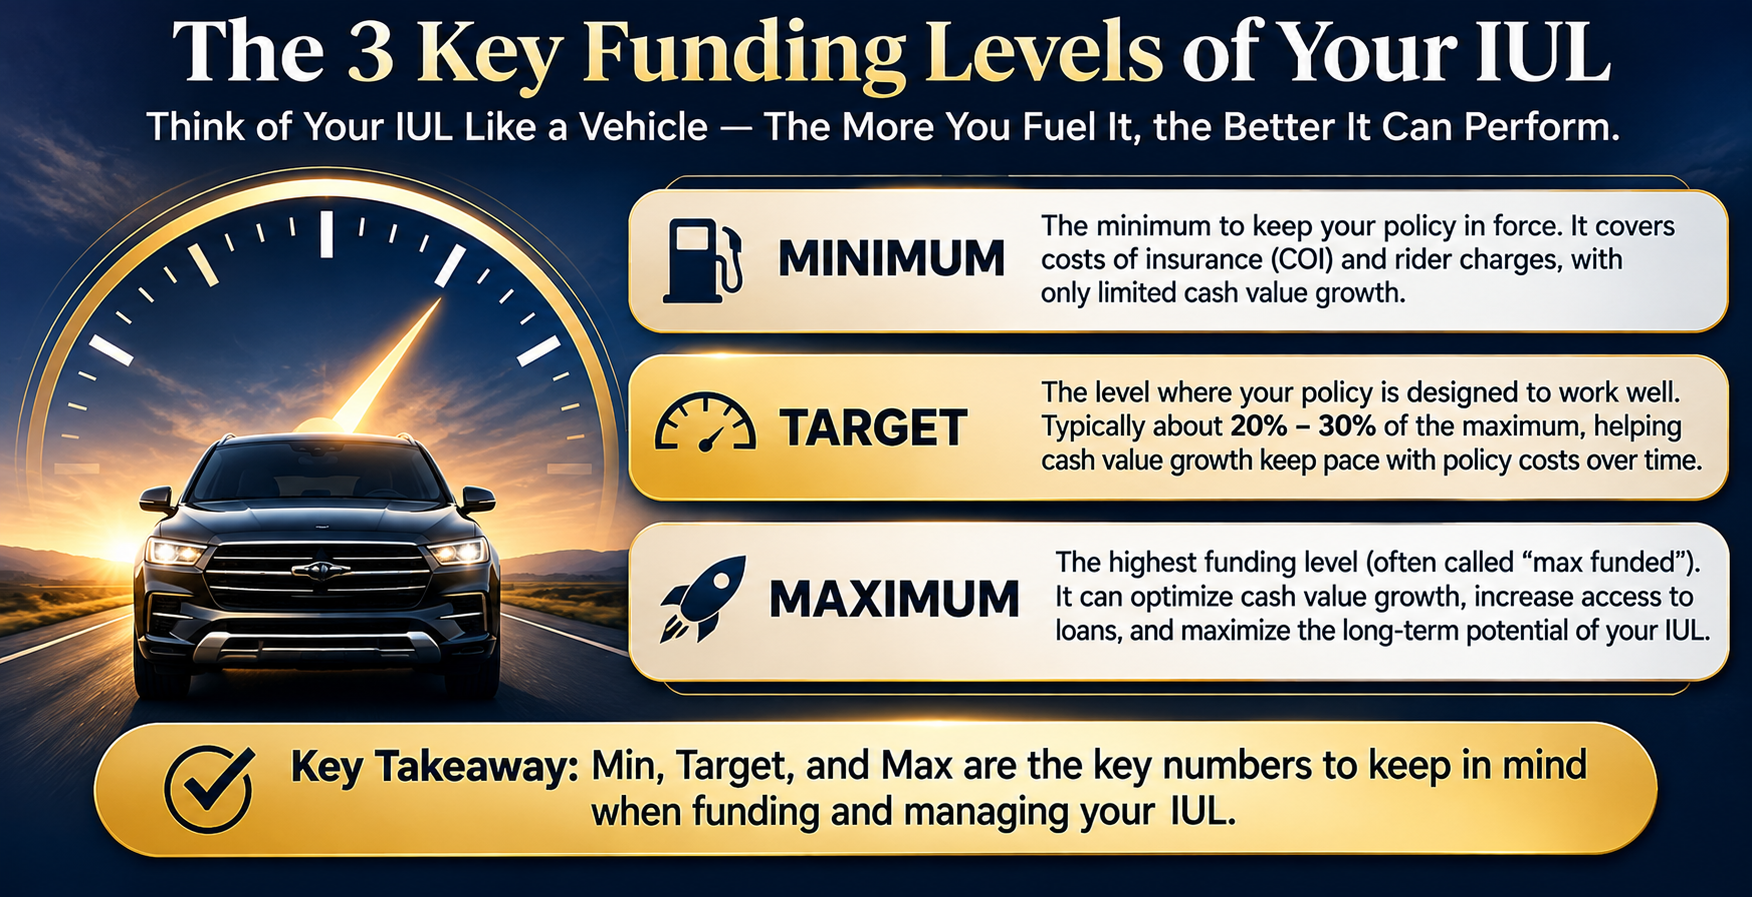
One of the most important things to understand about a flexible-premium IUL is how premium funding affects its long-term performance.
Subject to your policy's requirements and limitations, you may be able to vary premium contributions between different funding levels from year to year.
Minimum Funding
The lowest funding level used in a particular illustration or funding scenario. It may help cover policy expenses, cost of insurance, and rider charges, but may provide limited cash accumulation.
Target Funding
A planning benchmark used to evaluate a particular policy design. It can help illustrate a more substantial funding strategy, but it is not a universal guarantee of policy sustainability.
Maximum Funding
Funding toward the maximum premium permitted under applicable policy and tax rules, often with the objective of emphasizing cash-value accumulation.
Minimum Funding: Driving Below the Vehicle's Potential
You may choose to begin with lower contributions when your financial circumstances require it.
However, maintaining a policy at minimum funding may limit cash-value accumulation and increase the risk of future funding shortfalls.
Imagine purchasing a Lamborghini only to drive it at 5 miles per hour, or buying an airplane just to travel around the block.
You may not be using the vehicle in the way you originally intended.
Likewise, an IUL designed for significant cash-value accumulation may not achieve that objective when funded only at a low level.
Target Funding: Understanding the Design
Just as airplanes are engineered to operate within particular performance parameters, an IUL should be evaluated using a funding design appropriate for its intended purpose.
In some illustrations, a target contribution may represent approximately 20% to 30% of the illustrated maximum premium capacity.
This is an example of a possible design relationship, not a standard percentage that applies to every IUL.
At higher funding levels, accumulated policy value may help offset ongoing charges, but growth is not guaranteed and costs may rise over time.
Maximum Funding: Using More of the Capacity
The term "max-funded IUL" commonly describes a policy structured to accept substantial premiums while remaining within applicable life insurance tax limits.
Funding more money earlier may provide more time for potential interest credits to accumulate.
However, premium limits must be carefully monitored to avoid unintended Modified Endowment Contract (MEC) treatment.
Compound Growth: Why Time Matters.
One of the most important concepts in long-term financial planning is compounding.
A popular quotation often attributed to Albert Einstein calls compound interest the eighth wonder of the world and emphasizes the difference between earning and paying it.
The attribution to Einstein is not reliably established, but the financial principle remains useful.
This is the familiar compound-interest formula for a constant-rate investment with periodic compounding.
- A: Future accumulated amount.
- P: Initial principal balance.
- r: Annual interest rate.
- n: Number of compounding periods per year.
- t: Number of years.
Because time appears in the exponent, starting earlier can materially affect the future accumulated amount when positive returns compound.
Rollover Amounts: What Happens to Unused Capacity?
As discussed earlier, your policy may permit premiums within certain minimum and maximum funding limits.
Imagine that during a particular year you do not contribute the full amount that your policy could potentially accept.
In some policy designs, unused funding room may influence the amount that can be paid in a future year.
This creates an important planning question: Can you contribute additional money later when your financial circumstances change?
Year One
You fund less than the maximum permitted under the policy's current limits.
Future Years
The policy's premium capacity may change under applicable cumulative tax tests and contract rules.
Liquidity Event
You may want to contribute additional funds after receiving proceeds from a major financial event.
For example, perhaps you eventually sell your business or complete a significant real estate transaction.
You may want to evaluate whether part of those proceeds could be contributed to your existing IUL to support its cash-value strategy.
Available Cash: What Can You Actually Use?
When you deposit a check at a bank, you may see one amount listed as "available now" and another amount still awaiting availability.
This analogy can help you understand the difference between an IUL's accumulated policy value and the amount currently available upon surrender.
Account Value
The policy's accumulated value before applicable surrender deductions and outstanding loans. Your carrier may use terms such as Account Value, Accumulated Value, or Net Account Value, with definitions specific to its contract.
Cash Surrender Value
The amount available if the policy is fully surrendered, after applicable surrender charges, loans, and other contractual adjustments. This is not always the same as the maximum available policy loan.
An IUL may have accumulated account value even when the cash surrender value is relatively small or zero.
That does not mean there is no value inside the policy. It means contractual charges or other adjustments may limit what can currently be accessed.
Depending on the policy design, funding level, and available riders, cash value may be accessible during the first policy year.
In some illustrations, surrender charges decline over 10 or 13 years and may eventually disappear.
At that point, account value and cash surrender value may become much closer, assuming there are no outstanding loans or other deductions.
This is another reason why the timing of your policy purchase and the funding strategy deserve careful consideration.
Policy Loans: Accessing Cash Value.
One of the features of many permanent life insurance policies is the ability to borrow against available policy value.
This can provide liquidity for personal or business needs.
Think of the financial projects you may encounter throughout life:
- Purchasing or improving real estate.
- Supporting a business opportunity.
- Meeting an unexpected financial obligation.
- Supplementing retirement cash flow.
- Managing other planned liquidity needs.
Understanding your specific loan provisions is essential before using this feature.
Some IUL contracts offer different loan structures, including fixed loans and variable or indexed loans.
Fixed Policy Loans.
A fixed policy loan uses a contract-defined loan interest rate or interest-rate calculation.
Depending on the insurance carrier, the portion of account value securing the loan may receive a specified crediting rate.
Here is an example of loan terms from a particular policy illustration.
| Period | Loan Charge | Crediting / Net Example |
|---|---|---|
| Loan Account | Illustrative structure | 2.50% crediting rate; 2.00% guaranteed crediting rate in the cited example |
| Years 1–5 | 3.38% charged in advance, approximately 3.50% in arrears | Illustrated net rate: 1.00% current; 1.50% guaranteed |
| Years 6+ | 2.44% charged in advance, approximately 2.50% in arrears | Illustrated net rate: 0.00% current; 0.50% guaranteed |
These numbers are retained from the original educational example. They are not universal IUL rates and should not be interpreted as a current carrier quote.
Variable or Indexed Policy Loans.
Some IUL policies offer an indexed or variable loan option.
In certain contracts, these loans become available beginning in policy year three.
That is one reason why understanding the policy timeline matters when planning future liquidity.
With some indexed loan designs, the account value supporting the loan can remain allocated to index-linked crediting strategies.
This creates the possibility of receiving index interest credits while a loan remains outstanding.
For example, if the selected index strategy receives a favorable credit for the year, the policy's account value may benefit even though a policy loan exists.
Is There a Risk?
Yes.
Suppose the index performance is negative during a particular crediting period.
A strategy with a 0% index-crediting floor may receive no negative index interest credit for that segment.
However, loan interest can still be charged.
If the credited interest is less than the loan interest expense, the policy can experience a negative loan spread.
Favorable Scenario
Index-linked interest credits may exceed the loan interest rate, potentially supporting the policy's accumulated value.
Unfavorable Scenario
Index-linked credits may be zero or lower than loan interest expenses. Outstanding debt may grow faster than the policy's supporting value.
Understanding Your Allocation Options.
Just as you can choose different routes when driving a vehicle, some IUL contracts offer multiple interest-crediting allocations.
You may be able to divide eligible account value among a fixed account and several indexed strategies.
Here are the nine allocation examples from the original guide:
| # | Illustrative Allocation |
|---|---|
| 1 | Fixed Account |
| 2 | S&P 500 1-Year Point-to-Point (with Cap) |
| 3 | S&P 500 Monthly Point-to-Point (with Cap) |
| 4 | S&P 500 2-Year Point-to-Point (with Cap) |
| 5 | S&P 500 1-Year Point-to-Point (with Participation Rate and Cap) |
| 6 | Russell 2000 1-Year Point-to-Point (with Cap) |
| 7 | MSCI EAFE 1-Year Point-to-Point (with Cap) |
| 8 | BNPP MMA 1-Year Point-to-Point (Uncapped) |
| 9 | BNPP MMA 2-Year Point-to-Point (Uncapped) |
These are examples of possible allocation structures, not a statement that every IUL currently offers all nine.
The word "uncapped" does not mean unlimited guaranteed interest. Other contractual factors may limit credited returns.
Before your policy anniversary, contact your advisor to review your available allocation options and determine whether any changes are appropriate.
Some policies permit changes only on designated dates or for future segments, so review the specific rules in your contract.
Point-to-Point: Why Deposit Timing Matters.
An important feature of indexed crediting is the measurement period used to calculate interest.
A point-to-point strategy generally compares an index value at the beginning and end of a specified period, subject to the policy's crediting formula.
This is different from assuming that interest is credited every month.
Your Original Two-Year Example
Imagine you contributed money to your IUL in February 2022 and made another premium payment in June 2022.
Now suppose the amounts were assigned to separate two-year point-to-point segments beginning on those respective deposit dates.
February Contribution
If its two-year index segment began in February 2022, the segment would generally mature in February 2024.
June Contribution
If its two-year index segment began in June 2022, the segment would generally mature in June 2024.
This example demonstrates why the timing of premium payments and segment start dates can matter.
The sooner eligible money enters an interest-crediting segment, the sooner its particular measurement period can begin.
Every Good Vehicle Needs Regular Maintenance.
You would not drive an airplane for years without checking its instruments, fuel requirements, and operating condition.
Your IUL deserves similar attention.
Reviewing your policy regularly can help you understand whether it remains aligned with your financial objectives.
Review Funding
Compare premiums paid against your original and updated funding objectives.
Review Values
Check account value, cash surrender value, policy charges, and available loan capacity.
Review Loans
Evaluate loan balances, interest charges, index credits, and potential lapse risk.
Review Allocations
Understand your current segments, renewal dates, and available crediting choices.
Review Protection
Confirm death benefit structure, beneficiaries, and any applicable living-benefit riders.
Request an Illustration
Evaluate updated guaranteed and non-guaranteed projections using current policy data.
Learn to Drive Your Financial Vehicle.
An Indexed Universal Life policy can be a versatile financial vehicle for personal or business planning when appropriately designed and managed.
Like a car, an airplane, or a high-performance vehicle, its usefulness depends on understanding its capabilities, limitations, and operating requirements.
Remember the important concepts we have covered:
- Understand your policy's Specified Amount and death benefit.
- Know your minimum, target, and maximum funding figures.
- Understand how time and potential compounding affect accumulation.
- Verify future premium capacity before making large deposits.
- Distinguish account value from cash surrender value.
- Understand fixed and indexed policy loan provisions.
- Review allocation choices and crediting periods.
- Monitor your policy through regular reviews.
The goal is not simply to own a financial vehicle.
The goal is to understand how to use it responsibly in pursuit of your financial objectives.
If you have questions or concerns about your policy, contact your financial advisor.
Have Questions About Your IUL Policy?
Schedule a personal policy review with Vertex Financial Planning. We can discuss your funding, policy values, available loan options, allocations, and long-term objectives.
Schedule Your 60-Minute Policy ReviewOr email: info@vertexfinancialplanning.com